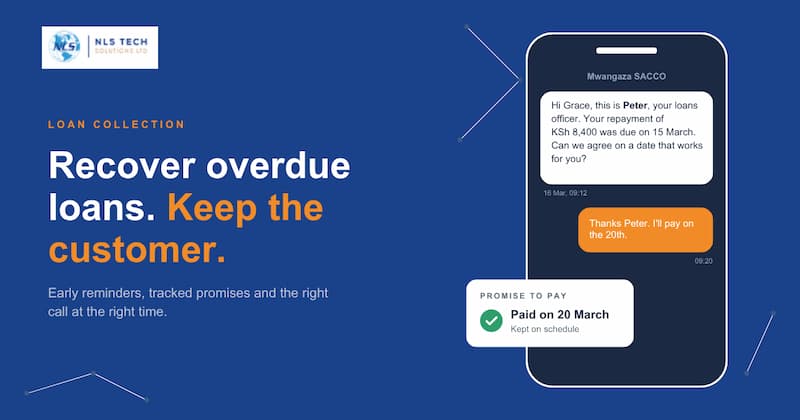
Loan Collection That Recovers Loans and Keeps Customers
.

Loan Collection That Recovers Loans and Keeps Customer

Read Time: 4 mins

Loan collection works best when it starts early and treats the borrower as a customer worth keeping. Tera Collect, the debt collection system from NLS Tech Solutions, helps banks, SACCOs and microfinance institutions do exactly that. It sends timely reminders, records every promise to pay and tells each officer who to call first. Accounts that need firmer action move to a supervisor automatically.

The result is fewer loans sliding into arrears and fewer customers lost along the way. In this article, we explain why loan collection so often damages relationships. The article follows one borrower and shows how the system works.

Reason Loan Collection Often Costs You the Customer

Bad loans weigh heavily on Kenyan lenders. Gross non-performing loans stood at 15.5 percent of bank loans in January 2026. Deposit-taking SACCOs averaged 5.88 percent in December 2025, according to SACCO Societies Regulatory Authority (SASRA). Most borrowers who miss a payment still intend to repay.
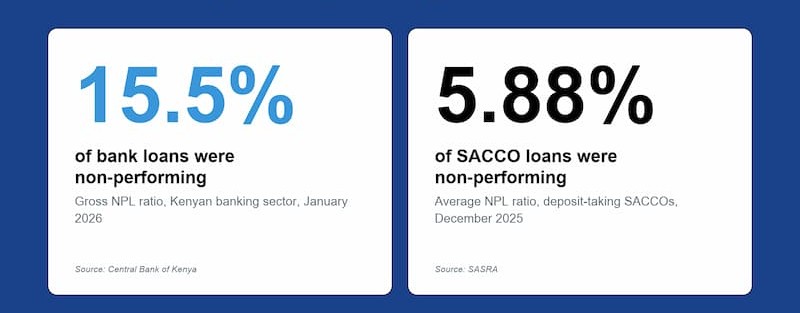
Gross non-performing loans stood at 15.5 percent of bank loans in January 2026. Deposit-taking SACCOs averaged 5.88 percent in December 2025, according to SACCO Societies Regulatory Authority (SASRA). Most borrowers who miss a payment still intend to repay.

Loan collection tends to go wrong in four ways.

  • It starts too late. Many teams wait until a loan is a month overdue. By then the borrower owes more and feels less able to catch up.
  • Officers work blind. Customer details sit in several systems. Officers lose time searching and often call an old number.
  • Promises get forgotten. A borrower promises to pay on Friday. Nobody checks, and the broken promise goes unnoticed for weeks.
  • The tone turns harsh. Pressure to hit targets leads to aggressive calls, and the customer stops picking up.

Each of these raises losses and pushes good customers towards other lenders.

Loan Collection: A SACCO Example

Grace is a dairy farmer and SACCO member with a KSh 200,000 development loan. In March, her milk buyer pays late and she misses a repayment.

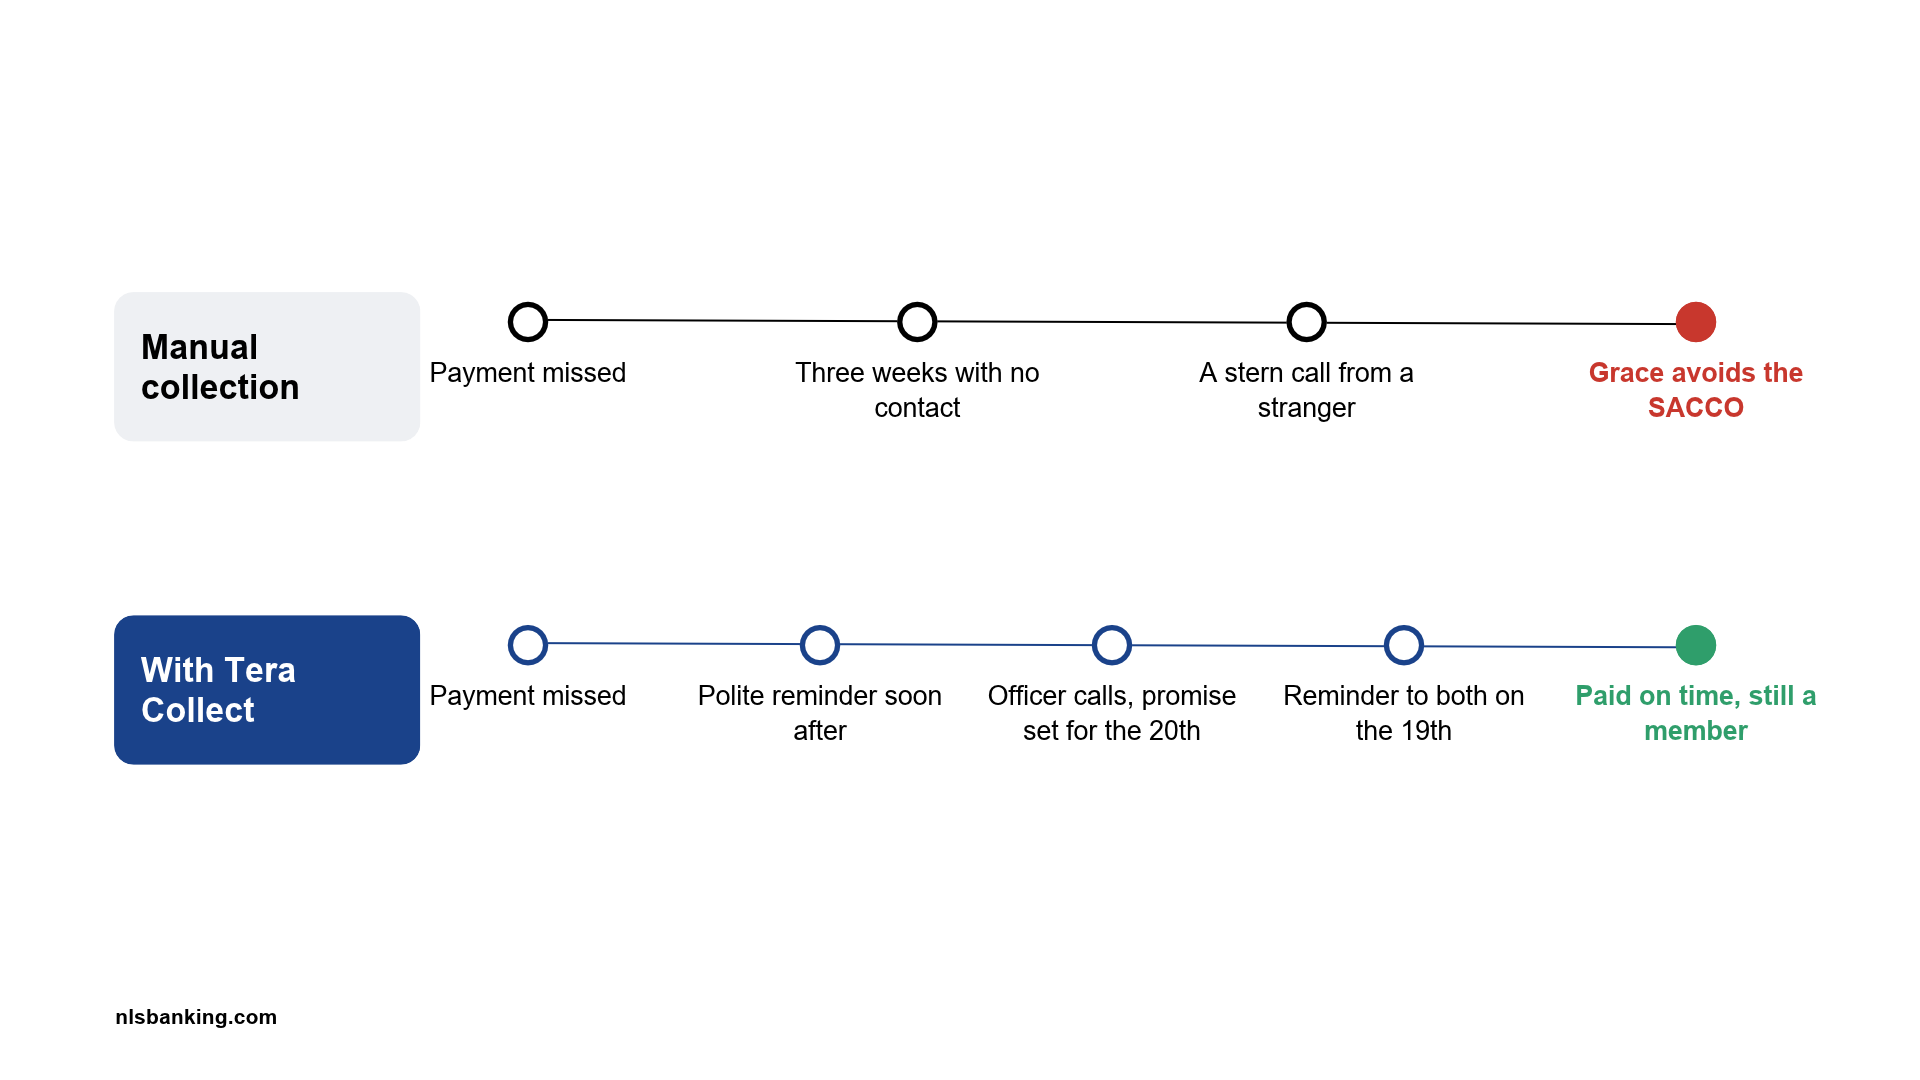
With manual loan collection, nothing happens for three weeks. Then an officer she has never met calls with a stern warning. Grace feels embarrassed and starts avoiding the SACCO.
Loan Collection: A SACCO Example

With Tera Collect, Grace gets a polite reminder soon after the due date. Her officer sees the account on a morning list and calls that week. Grace promises to pay on the 20th, and the system records the promise. On the 19th, both Grace and the officer get a reminder. She pays on time and stays a loyal member.

How Loan Collection Works With Tera Collect

The system connects to your core banking system and pulls in loan, guarantor and repayment data in real time. Each officer works from one complete view of the customer. Loan collection then follows six steps.

  1. Early reminders. Reminders go out automatically based on days in arrears, so many borrowers catch up on their own.
  2. Automatic assignment. Overdue accounts go to officers by arrears bucket and officer profile.
  3. Who to call first. Accounts are ranked by likelihood to pay and urgency. Machine learning suggests the best time to call.
  4. Promise tracking. Every promise to pay is recorded with its date. Officers get a morning email listing promises due.
  5. Escalation. An account that slips into a worse bucket with no activity moves to a supervisor.
  6. Finding borrowers. Alternative numbers, employers and relatives help officers reach customers who have moved.

What Does Better Loan Collection Change for Your Institution?

Good loan collection shows up in the numbers and in how customers feel about you.

  • More loans cure themselves. Early reminders bring many borrowers back on track before an officer needs to call.
  • Officers spend time where it counts. Ranked lists point them to accounts most likely to pay.
  • Fewer broken promises slip through. Every promise is tracked, and both sides get a reminder before it falls due.
  • Faster recovery. The time from first missed payment to settlement gets shorter.
  • Clear team targets. Managers can set and track goals for in-house and external collectors.
  • Lower risk of complaints. Every contact attempt is logged, which supports compliance with collection rules.

Most importantly, borrowers like Grace keep banking with you after they recover.

Loan Collection Habits That Keep Customers

A system helps, but loan collection still depends on how your team treats people. These habits make a real difference.

  • Contact borrowers in the first week. A short, friendly reminder works better than a firm call a month later.
  • Make reminders personal. One study added the loan officer’s name to SMS reminders. Loans still unpaid a month after maturity fell by 41 percent. The effect held for repeat borrowers who knew that officer.
  • Ask before you demand. Find out why the payment was missed, then agree on a date the borrower can meet.
  • Keep every promise on record. Follow up the day after a promise falls due.
  • Match the tone to the stage. Save firm language for borrowers who stop responding.
  • Thank borrowers who catch up. A short message after payment builds goodwill for the next loan.
  • Review results monthly. Reporting tools show which reminders and call times bring in the most repayments.

Start Recovering More With Better Loan Collection

Every overdue loan is also a customer relationship. Loan collection that starts early, tracks every promise and keeps the tone respectful recovers more money. It also keeps the borrower coming back for the next loan.

Tera Collect gives your collections team the tools to work this way, using the core banking system you already have. To see how it would fit your institution, request a demo from the NLS team.
Categories
Latest Posts
Core-Dependent Architectures Are No Longer Enough for Digital Banking

Core-Dependent Architectures Are No Longer Enough for Digital Banking

Core-dependent architectures are no longer enough to sustain the scale, speed, and resilience required in today’s digital banking environment. Over the past decade, transaction volumes across mobile banking, internet platforms, agency networks, and third-party integrations have grown exponentially. Yet in many institutions, the architectural principle has remained unchanged: every meaningful digital transaction must pass through the core banking system in real time. At low volumes, this dependency is manageable.At digital scale, it becomes a structural constraint. Yet despite modern interfaces…
Core-Dependent Architectures Are No Longer Enough for Digital Banking

Core-Dependent Architectures Are No Longer Enough for Digital Banking

Core-dependent architectures are no longer enough to sustain the scale, speed, and resilience required in today’s digital banking environment. Over the past decade, transaction volumes across mobile banking, internet platforms,…
Core-Dependent Architectures Are No Longer Enough for Digital Banking
Core-dependent architectures are no longer enough to sustain the scale, speed, and resilience required in today’s digital banking environment. Over the past decade, transaction volumes across mobile banking, internet platforms, agency networks, and third-party integrations have grown exponentially. Yet in many institutions, the architectural principle has remained unchanged: every meaningful digital transaction must pass through the core banking system in real time. At low volumes, this dependency is manageable.At digital scale, it becomes a structural constraint. Yet despite modern interfaces…

Core-Dependent Architectures Are No Longer Enough for Digital Banking

Core-Dependent Architectures Are No Longer Enough for Digital Banking
Core-dependent architectures are no longer enough to sustain the scale, speed, and resilience required in today’s digital banking environment. Over the past decade, transaction volumes across mobile banking, internet platforms,…

Core-Dependent Architectures Are No Longer Enough for Digital Banking

Core-dependent architectures are no longer enough to sustain the scale, speed, and resilience required in today’s digital banking environment. Over the past decade, transaction volumes across mobile banking, internet platforms,…
Core-Dependent Architectures Are No Longer Enough for Digital Banking
Core-dependent architectures are no longer enough to sustain the scale, speed, and resilience required in today’s digital banking environment. Over the past decade, transaction volumes across mobile banking, internet platforms, agency networks, and third-party integrations have grown exponentially. Yet in many institutions, the architectural principle has remained unchanged: every meaningful digital transaction must pass through the core banking system in real time. At low volumes, this dependency is manageable.At digital scale, it becomes a structural constraint. Yet despite modern interfaces…
Omnichannel platforms are the New Core

Omnichannel Platforms Are the New Core

For decades, the core banking system (CBS) has been regarded as the heart of a financial institution. It has been the main handler of accounts, transactions, and customer records, powering everything from teller operations to back-office reconciliation. But as customer behavior shifts, competition intensifies, and Omnichannel platforms are rising. That long-held view is undergoing a fundamental redefinition. Omnichannel platforms have become the new core. They are no longer simply “front ends” or convenience layers. They are the primary arena where…
Omnichannel platforms are the New Core

Omnichannel Platforms Are the New Core

For decades, the core banking system (CBS) has been regarded as the heart of a financial institution. It has been the main handler of accounts, transactions, and customer records, powering…
Omnichannel platforms are the New Core
For decades, the core banking system (CBS) has been regarded as the heart of a financial institution. It has been the main handler of accounts, transactions, and customer records, powering everything from teller operations to back-office reconciliation. But as customer behavior shifts, competition intensifies, and Omnichannel platforms are rising. That long-held view is undergoing a fundamental redefinition. Omnichannel platforms have become the new core. They are no longer simply “front ends” or convenience layers. They are the primary arena where…

Omnichannel Platforms Are the New Core

Omnichannel platforms are the New Core
For decades, the core banking system (CBS) has been regarded as the heart of a financial institution. It has been the main handler of accounts, transactions, and customer records, powering…

Omnichannel Platforms Are the New Core

For decades, the core banking system (CBS) has been regarded as the heart of a financial institution. It has been the main handler of accounts, transactions, and customer records, powering…
Omnichannel platforms are the New Core
For decades, the core banking system (CBS) has been regarded as the heart of a financial institution. It has been the main handler of accounts, transactions, and customer records, powering everything from teller operations to back-office reconciliation. But as customer behavior shifts, competition intensifies, and Omnichannel platforms are rising. That long-held view is undergoing a fundamental redefinition. Omnichannel platforms have become the new core. They are no longer simply “front ends” or convenience layers. They are the primary arena where…
99.9% uptime is not enough, 99.99% is

99.9% Uptime Alone is Not Enough, 99.99% is

A system downtime, whether planned, brief, or carried out as intended, can have real consequences for a financial institution. For a user, it is still a disruption. Customers expect to access their accounts 24/7. It is a customer expectation vs business promise. And 99.9% uptime alone is not enough. Customers Want 24/7 Banking Promise   According to recent data from Statista, Over 73% of banking customers in Asia-Pacific use digital services weekly, and more than 60% expect them to be…
99.9% uptime is not enough, 99.99% is

99.9% Uptime Alone is Not Enough, 99.99% is

A system downtime, whether planned, brief, or carried out as intended, can have real consequences for a financial institution. For a user, it is still a disruption. Customers expect to…
99.9% uptime is not enough, 99.99% is
A system downtime, whether planned, brief, or carried out as intended, can have real consequences for a financial institution. For a user, it is still a disruption. Customers expect to access their accounts 24/7. It is a customer expectation vs business promise. And 99.9% uptime alone is not enough. Customers Want 24/7 Banking Promise   According to recent data from Statista, Over 73% of banking customers in Asia-Pacific use digital services weekly, and more than 60% expect them to be…

99.9% Uptime Alone is Not Enough, 99.99% is

99.9% uptime is not enough, 99.99% is
A system downtime, whether planned, brief, or carried out as intended, can have real consequences for a financial institution. For a user, it is still a disruption. Customers expect to…

99.9% Uptime Alone is Not Enough, 99.99% is

A system downtime, whether planned, brief, or carried out as intended, can have real consequences for a financial institution. For a user, it is still a disruption. Customers expect to…
99.9% uptime is not enough, 99.99% is
A system downtime, whether planned, brief, or carried out as intended, can have real consequences for a financial institution. For a user, it is still a disruption. Customers expect to access their accounts 24/7. It is a customer expectation vs business promise. And 99.9% uptime alone is not enough. Customers Want 24/7 Banking Promise   According to recent data from Statista, Over 73% of banking customers in Asia-Pacific use digital services weekly, and more than 60% expect them to be…
Digital Channels are the Bank

Digital Banking Channels Are The Bank

Digital banking channels are today not just extensions of the bank, Sacco or Microfinance bank. These channels are the bank. According to data published by the Statista Research Department on June 3, 2025, digital banking channels had already seen widespread adoption among Kenyan bank customers by 2022. Importantly, usage rates had increased across all banking channels. However, it’s worth noting that 2022 is a relatively distant benchmark in the fast-evolving tech landscape. It’s likely that an even broader range of…
Digital Channels are the Bank

Digital Banking Channels Are The Bank

Digital banking channels are today not just extensions of the bank, Sacco or Microfinance bank. These channels are the bank. According to data published by the Statista Research Department on…
Digital Channels are the Bank
Digital banking channels are today not just extensions of the bank, Sacco or Microfinance bank. These channels are the bank. According to data published by the Statista Research Department on June 3, 2025, digital banking channels had already seen widespread adoption among Kenyan bank customers by 2022. Importantly, usage rates had increased across all banking channels. However, it’s worth noting that 2022 is a relatively distant benchmark in the fast-evolving tech landscape. It’s likely that an even broader range of…

Digital Banking Channels Are The Bank

Digital Channels are the Bank
Digital banking channels are today not just extensions of the bank, Sacco or Microfinance bank. These channels are the bank. According to data published by the Statista Research Department on…

Digital Banking Channels Are The Bank

Digital banking channels are today not just extensions of the bank, Sacco or Microfinance bank. These channels are the bank. According to data published by the Statista Research Department on…
Digital Channels are the Bank
Digital banking channels are today not just extensions of the bank, Sacco or Microfinance bank. These channels are the bank. According to data published by the Statista Research Department on June 3, 2025, digital banking channels had already seen widespread adoption among Kenyan bank customers by 2022. Importantly, usage rates had increased across all banking channels. However, it’s worth noting that 2022 is a relatively distant benchmark in the fast-evolving tech landscape. It’s likely that an even broader range of…
Customers want these mobile banking app features

Customers Want These Mobile Banking App Features

More and more customers today are turning to their smartphones for banking. None of them wants to be left out in the modern banking experience.   As of 2020, mobile banking was the main channel adopted in Kenya in all age groups. The utilization was higher among younger respondents aged 26-35 years. –Statista 2020 and Now is a Long Time   Mobile banking usage in Kenya has likely increased. Thanks to more convenient features that have been added along the…
Customers want these mobile banking app features

Customers Want These Mobile Banking App Features

More and more customers today are turning to their smartphones for banking. None of them wants to be left out in the modern banking experience.   As of 2020, mobile…
Customers want these mobile banking app features
More and more customers today are turning to their smartphones for banking. None of them wants to be left out in the modern banking experience.   As of 2020, mobile banking was the main channel adopted in Kenya in all age groups. The utilization was higher among younger respondents aged 26-35 years. –Statista 2020 and Now is a Long Time   Mobile banking usage in Kenya has likely increased. Thanks to more convenient features that have been added along the…

Customers Want These Mobile Banking App Features

Customers want these mobile banking app features
More and more customers today are turning to their smartphones for banking. None of them wants to be left out in the modern banking experience.   As of 2020, mobile…

Customers Want These Mobile Banking App Features

More and more customers today are turning to their smartphones for banking. None of them wants to be left out in the modern banking experience.   As of 2020, mobile…
Customers want these mobile banking app features
More and more customers today are turning to their smartphones for banking. None of them wants to be left out in the modern banking experience.   As of 2020, mobile banking was the main channel adopted in Kenya in all age groups. The utilization was higher among younger respondents aged 26-35 years. –Statista 2020 and Now is a Long Time   Mobile banking usage in Kenya has likely increased. Thanks to more convenient features that have been added along the…
No Comments

Leave a Comment

Email
Please enter a valid email address.
Comment *
Fill out this field

Related Posts
Omnichannel platforms are the New Core
.

Omnichannel Platforms Are the New Core

For decades, the core banking system (CBS) has been regarded as the heart of a financial institution. It has been the main handler of accounts, transactions, and customer records, powering…
Read More

Contact Us

Get in Touch
Today.

Engage with us now and take the first step towards transformative solutions.
Cal Us On +254-20-263 2768

Saachi Plaza, Ground Floor – C2Argwings Kodhek Rd, Kilimani, Nairobi, Kenya

    Menu